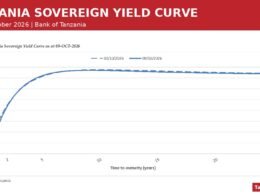

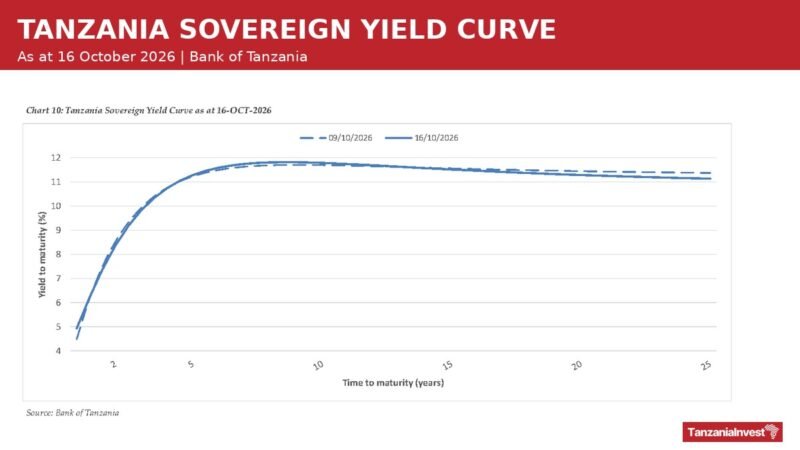
Tanzania’s financial markets closed the week to 16 October 2026 with the 25-year Treasury bond yield falling to 10.8422% at a heavily oversubscribed auction, down from 11.4799% at the previous auction of the same tenor.
The Bank of Tanzania (BOT) released the figures on 19 October 2026 in its eighth Domestic Financial Markets Weekly Report, a publication it launched on 2 September 2026 and now issues weekly.
The report consolidates foreign exchange market, money market and government securities data for the trading week that ran from 12 to 16 October 2026, alongside charts of monthly and fiscal-year trends.
Government Securities
The 13.25% 25-year Treasury bond No. 722, maturing on 16 October 2051, attracted 2,547 bids at the auction held on 14 October 2026, of which 1,673 were successful.
Investors tendered TZS 2,495.06 billion against an offered amount of TZS 414.19 billion, an oversubscription of TZS 2,080.87 billion that produced a bid-to-cover ratio of 6.02x, with total allotment reaching TZS 610.61 billion.
The minimum successful price was 115.5000 and the weighted average price 116.3067, leaving the weighted average yield to maturity 63.77 basis points below the level recorded at the preceding auction of the same tenor.
Banks submitted 27.51% of subscriptions and took the largest share of the allotment at TZS 343.50 billion, equivalent to 56.25% of the total.
Individuals and Companies accounted for 25.42% of subscriptions and were allotted TZS 191.30 billion, representing 31.33% of the total allotment.
Brokers submitted 24.40% of subscriptions but received just TZS 8.72 billion, or 1.43% of the allotment, while Collective Investment Schemes tendered 15.34% of subscriptions and received nothing.
Insurance Companies were allotted 6.53% of the total from only 2.20% of subscriptions, while Pension Funds received 0.64% of the allotment from 4.32% of subscriptions.
Outstanding Government Securities stood at TZS 34,015.15 billion, comprising Treasury bonds worth TZS 30,560.85 billion, or 89.84% of the total, and Treasury bills worth TZS 3,454.30 billion, or 10.16%.
Banks held the largest share of that stock at 34.17%, worth TZS 11,622.51 billion, followed by Pension Funds at 29.76%, worth TZS 10,121.28 billion.
Retail Investors held 17.92% worth TZS 6,094.25 billion, Collective Investment Schemes and other official entities 7.98% worth TZS 2,715.64 billion, and Insurance Companies 7.30% worth TZS 2,484.06 billion.
The Bank onboarded 3,600 new clients in the current fiscal year, lifting the total number of registered investors in government securities to 35,102.
The next government securities auction is scheduled for Wednesday 21 October 2026, when Treasury bills will be offered in line with the issuance calendar.
Foreign Exchange Market
The shilling depreciated 0.07% over the week to close at TZS 2,633.12 against the US dollar, from TZS 2,631.36 at the end of the previous week.
Turnover on the Interbank Foreign Exchange Market (IFEM) fell to USD 19.70 million from USD 22.30 million a week earlier, while retail foreign exchange transactions rose to USD 604.89 million from USD 533.81 million.
Trade accounted for the largest share of retail turnover at USD 181.28 million, followed by Mining at USD 74.18 million and Agriculture at USD 73.01 million, together representing USD 328.47 million.
Daily retail foreign exchange transactions averaged USD 124.06 million over the past month, with sales averaging USD 61.74 million and purchases averaging USD 62.31 million.
Against other currencies the shilling closed at TZS 3,487.83 to the British Pound Sterling, TZS 2,950.67 to the Euro, TZS 393.52 to the Chinese Yuan and TZS 20.25 to the Kenyan Shilling.
Money Market
The Interbank Cash Market (IBCM) 7-day Weighted Average Rate (WAR) closed the week at 6.68%, down from 6.75% recorded at the close of the previous week.
Total 7-day trading volume increased to TZS 812.65 billion from TZS 748.35 billion recorded in the preceding week, according to the report.
The 7-day weekly WAR averaged 6.41%, sitting 16 basis points above the Central Bank Rate (CBR) of 6.25% and inside the corridor of 4.75% to 7.75%.
The Bank injected TZS 892.50 billion through 7-day reverse repurchase agreements at the CBR of 6.25%, up sharply from TZS 252.43 billion injected in the preceding week.
Bank of Tanzania Monetary Policy Framework
The Bank of Tanzania adopted an interest rate based monetary policy framework in January 2024, abandoning the monetary targeting regime under which it had previously controlled the growth of reserve money.
Within that framework the Central Bank Rate functions as the headline policy rate, while the 7-day interbank cash market rate serves as the operating target that the Bank nudges towards it.
It steers that target using repurchase and reverse repurchase agreements, 35-day and 91-day Treasury bills, the statutory minimum reserve requirement, and direct purchases or sales of foreign currency on the interbank market.
The Monetary Policy Committee maintained the CBR at 6.25% for the fourth quarter of 2026, and that rate, together with its 4.75% to 7.75% corridor, continues to frame this week’s money market readings.
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free