


During Week 42 of 2026, spanning October 12th to October 16th, equity turnover on the Dar es Salaam Stock Exchange fell sharply -28.16% compared with Week 41 of 2026, with MUCOBA (+7.79%) emerging as the top gainer, in a four-day trading week shortened by Nyerere Day on October 14th.
Throughout this report, individual stock and index percentage changes reflect close-to-close moves between 9th October 2026 (Week 41 of 2026 closing day) and 16th October 2026 (Week 42 of 2026 closing day). Turnover, volume and deals comparisons reflect totals across the full trading weeks.
Equity Turnover and Volume
Equity Turnover excluding ETF trades reached TZS 12.94 billion, a sharp decline of -28.16% compared to Week 41 of 2026’s TZS 18.02 billion.
A total of 5,295,373 shares changed hands across 14,917 deals, a sharp decline of -25.36% versus Week 41 of 2026’s 7,095,006 shares.
CRDB led all counters by volume with 2,908,156 shares traded, while CRDB dominated by turnover, generating TZS 8.44 billion.
CRDB, NMB, VODA, and TCCL have been consistent fixtures among the top five counters by turnover across recent weeks.
ETF Trading
ETF trading across the two listed funds generated combined turnover of TZS 726.74 million on volume of 3,759,220 units, a -30.68% decline versus Week 41 of 2026’s TZS 1.05 billion.
| ETF | Closing Price (TZS) 9th October 2026 | Closing Price (TZS) 16th October 2026 | Variation |
|---|---|---|---|
| IEACLC-ETF | 1,460 | 1,450 | -0.68% |
| VERTEX-ETF | 320 | 315 | -1.56% |
| ZAN-ETF | — | 115 | — |
Foreign Investor Activity
Local investors accounted for 99.90% of buying and 71.12% of selling, against foreign investor shares of 0.10% and 28.88% respectively, producing a net foreign net selling position of USD 1,414,413 for the week.
This result extends a four-week streak of foreign net selling on the exchange.
| % Local Buying | % Foreign Buying | % Local Selling | % Foreign Selling | Net Foreign Flow (USD) |
|---|---|---|---|---|
| 99.90% | 0.10% | 71.12% | 28.88% | -1,414,413 |
Market Capitalisation
Total market capitalisation closed Week 42 of 2026 at TZS 39,861.61 billion, a -0.54% change versus Week 41 of 2026’s TZS 40,077.28 billion.
Domestic market capitalisation settled at TZS 27,403.22 billion, reflecting a -0.62% decline from Week 41 of 2026.
ETF market capitalisation rose to TZS 247.71 billion, a +3.81% gain over the prior week.
| Measure | 9th October 2026 (TZS billion) | 16th October 2026 (TZS billion) | Variation |
|---|---|---|---|
| Total Market Capitalisation | 40,077.28 | 39,861.61 | -0.54% |
| Domestic Market Capitalisation | 27,574.29 | 27,403.22 | -0.62% |
| ETF Market Capitalisation | 238.62 | 247.71 | +3.81% |
Indexes
Three of the five Dar es Salaam Stock Exchange indices retreated from Week 41 of 2026 levels, with the Banks, Finance & Investment index posting the steepest move at -1.62%.
The All Share Index (DSEI) edged down -0.54%, the Tanzania Share Index (TSI) slipped -0.62%, the Industrial & Allied index gained +1.74%, the Banks, Finance & Investment index (BI) fell -1.62%, and the Commercial Services index rose +0.74%.
Notably, the DSEI, TSI, and BI have each now declined for three consecutive weeks.
| Index | Closing Value 9th October 2026 | Closing Value 16th October 2026 | Variation |
|---|---|---|---|
| All Share Index (DSEI) | 4,597.48 | 4,572.74 | -0.54% |
| Tanzania Share Index (TSI) | 10,142.06 | 10,079.13 | -0.62% |
| Industrial & Allied (IA) | 5,034.51 | 5,122.17 | +1.74% |
| Banks, Finance & Investment (BI) | 22,842.38 | 22,471.84 | -1.62% |
| Commercial Services (CS) | 3,531.40 | 3,557.70 | +0.74% |
Stock Performances
MUCOBA led all gainers with a rise of +7.79% versus Week 41 of 2026, followed by TCCL, which advanced +5.26%, and KA, which posted a gain of +4.35%.
On the losing side, JATU suffered the steepest decline at -14.81%, with TOL falling -8.70% and NMG retreating -6.15%.
MKCB and TCC have each recorded gains for at least three consecutive weeks.
NMB has declined for at least three consecutive weeks.
| Stock | Closing Price (TZS) 9th October 2026 | Closing Price (TZS) 16th October 2026 | Variation |
|---|---|---|---|
| AFRIPRISE | 710 | 725 | +2.11% |
| CRDB | 2,900 | 2,830 | -2.41% |
| DCB | 395 | 395 | 0.00% |
| DSE | 6,410 | 6,170 | -3.74% |
| EABL | 5,870 | 5,820 | -0.85% |
| JATU | 270 | 230 | -14.81% |
| JHL | 8,700 | 8,700 | 0.00% |
| KA | 115 | 120 | +4.35% |
| KCB | 2,190 | 2,180 | -0.46% |
| MBP | 2,070 | 2,030 | -1.93% |
| MCB | 385 | 375 | -2.60% |
| MKCB | 3,760 | 3,820 | +1.60% |
| MUCOBA | 385 | 415 | +7.79% |
| NICO | 3,770 | 3,580 | -5.04% |
| NMB | 2,010 | 1,990 | -1.00% |
| NMG | 325 | 305 | -6.15% |
| PAL | 290 | 300 | +3.45% |
| SWALA | 450 | 450 | 0.00% |
| SWIS | 2,500 | 2,450 | -2.00% |
| TBL | 9,680 | 9,810 | +1.34% |
| TCC | 13,380 | 13,510 | +0.97% |
| TCCL | 3,800 | 4,000 | +5.26% |
| TOL | 1,840 | 1,680 | -8.70% |
| TPCC | 5,670 | 5,820 | +2.65% |
| TTP | 425 | 420 | -1.18% |
| USL | 30 | 30 | 0.00% |
| VODA | 1,270 | 1,280 | +0.79% |
| YETU | 510 | 510 | 0.00% |
Bond Market
Bond turnover totaled TZS 132.55 billion across 66 deals, a surge of +71.36% compared to Week 41 of 2026’s TZS 77.35 billion.
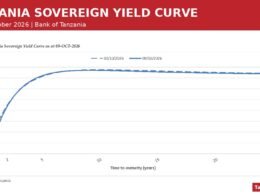
The yield curve exhibited a flattening bias, with the 5-year yield declining -23.5 basis points to 10.0202% while the 25-year yield fell a steeper -59.8 basis points to 10.8124%.
The 20-year tenor was a notable exception, with its yield rising +34.2 basis points to 12.0873%, diverging sharply from the broader downward trend across the curve.
| Tenor | Coupon (weighted avg) | Weighted Average Yield 16th October 2026 | Weighted Average Yield 9th October 2026 | Change (bps) | Trade Count | Face Value Traded (TZS billion) |
|---|---|---|---|---|---|---|
| 5Y | 10.2554% | 10.0202% | 10.2549% | -23.5 | 5 | 7.1370 |
| 10Y | — | — | — | — | 0 | — |
| 15Y | 12.2502% | 10.3641% | 10.6826% | -31.9 | 14 | 104.9773 |
| 20Y | 12.8993% | 12.0873% | 11.7457% | +34.2 | 22 | 1.6600 |
| 25Y | 14.5207% | 10.8124% | 11.4108% | -59.8 | 21 | 6.6836 |
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free