
The Dar es Salaam Stock Exchange (DSE) Market Review for August 2026 by Kadoo Securities shows the DSE share index up 7.4% while equity turnover fell 67% month on month to TZS 146.4 billion, with domestic counters adding TZS 1.85 trillion in value.
Kadoo Securities Co. Limited is a Tanzanian securities brokerage and investment advisory firm whose research department publishes this Dar es Salaam Stock Exchange market review every month, covering DSE trading activity, order-book behaviour and stock selection.
The August 2026 edition was prepared by analysts Abraham Ukhotya and Erick Sindatuma using market prices, turnover and order-book data available through 31 August 2026.
Executive Summary

August’s rally was driven primarily by a single corporate catalyst rather than by broad market sentiment.
NMB Bank Plc (DSE: NMB) announced a share split during the month, and its implementation on 24 August triggered a final-week gain of 20% that lifted the counter’s full-month return to 20.02%.
Domestic counters added TZS 1.85 trillion of value over the month as the Tanzania Share Index advanced 7.4%.
Equity turnover of TZS 146.4 billion was spread across 20 trading sessions, with the final full week of the month alone contributing 35.8% of that total.
Foreign investors remained net sellers of TZS 32.8 billion during August, but domestic buyers absorbed the outflow and accounted for 99.75% of the local buy side without derailing the rally.
The month’s ten strongest price performers were led by TOL Gases Limited (DSE: TOL) and Mwalimu Commercial Bank Plc (DSE: MCB), ahead of NMB in third place.
- TOL Gases Limited (DSE: TOL): 38.6%
- Mwalimu Commercial Bank Plc (DSE: MCB): 29.0%
- NMB Bank Plc (DSE: NMB): 20.02%
- TATEPA (DSE: TTP): 11.6%
- Maendeleo Bank (DSE: MBP): 11.5%
- National Investment Company Limited (DSE: NICO): 9.3%
- MUCOBA Bank (DSE: MUCOBA): 7.1%
- DCB Commercial Bank (DSE: DCB): 5.6%
- KCB Group (DSE: KCB): 5.3%
- Vodacom Tanzania Plc (DSE: VODA): 5.0%
Kadoo’s monthly outlook favours staying constructive and selective, positioning for bank earnings as accelerating private-sector credit and M3 money-supply growth expand the sector’s earnings base, though margins and asset quality remain the key watchpoints.
Pending dividend declarations at National Investment Company Limited and Afriprise Investment Plc (DSE: AFRIPRISE) remain potential near-term share-price catalysts, though expectations may already be partly priced in.
August Market Structure

Weekly turnover data show that liquidity was concentrated late in the month, with the week of 24 to 28 August alone contributing TZS 52.4 billion, or 35.8% of the month’s total equity turnover.
Turnover in the other four weeks measured TZS 25.8 billion, TZS 30.0 billion, TZS 23.3 billion and TZS 14.9 billion for the weeks of 3 to 7 August, 10 to 14 August, 17 to 21 August and 31 August respectively.
NMB and CRDB Bank Plc (DSE: CRDB) together accounted for 85.2% of total August turnover, with NMB contributing 58.3% and CRDB contributing 26.9% of market activity.

Each counter’s August price change is checked here against its trading depth, to separate genuine demand from thin, event-driven moves.
NMB’s 20.02% gain was matched by deep turnover of TZS 85.34 billion across 21,837 deals, confirming broad post-split demand rather than speculative pricing.
CRDB, by contrast, recorded heavy participation of TZS 39.39 billion across 29,265 deals while its price rose just 0.8%, a pattern that points to strong supply absorption.
TOL’s 38.6% gain occurred on turnover of only TZS 0.27 billion across 981 deals, a thin book supporting a large price move rather than durable demand.
How the Picks Were Selected

The monthly stock picks are built from observable trading execution rather than price momentum alone, using a five-lens framework.
The five lenses are demand confirmation based on price direction and turnover, execution depth based on deals and active trading sessions, participation based on traded volume, market pressure based on the balance of bids and offers, and investor motive based on catalysts, valuation and income.
Applying that framework, the five picks for August are NMB, CRDB, Vodacom Tanzania Plc, Tanzania Cigarette Company Plc (DSE: TCC) and National Investment Company Limited.
TOL Gases Limited was excluded from the picks despite its large August gain: it remains an event-driven watch, pending clarity on the terms of its expected rights issue.
The Five Monthly Stock Picks
Each pick below is supported by its own trading evidence and a distinct investor motive, ranging from the post-split demand behind NMB to the income case for TCC.
NMB Bank Plc

NMB shares held in a tight range between TZS 1,775 and TZS 1,784 through 21 August before rising in every subsequent session.
The counter reached a high of TZS 2,120 on 28 August before easing to close the month at TZS 2,110.
Bids dominated NMB’s order-book through the rally, but the book flipped entirely to offers by 31 August with no bid side present.
Block trades rose from 9.2% of NMB’s turnover before the split to 45.7% afterward, including a single block of 7.36 million shares on 27 August that represented 74.1% of that day’s volume.
The parabolic price action broadened access to the counter, but Kadoo cautions that the month-end offer wall argues for disciplined entries rather than chasing the rally.
CRDB Bank Plc
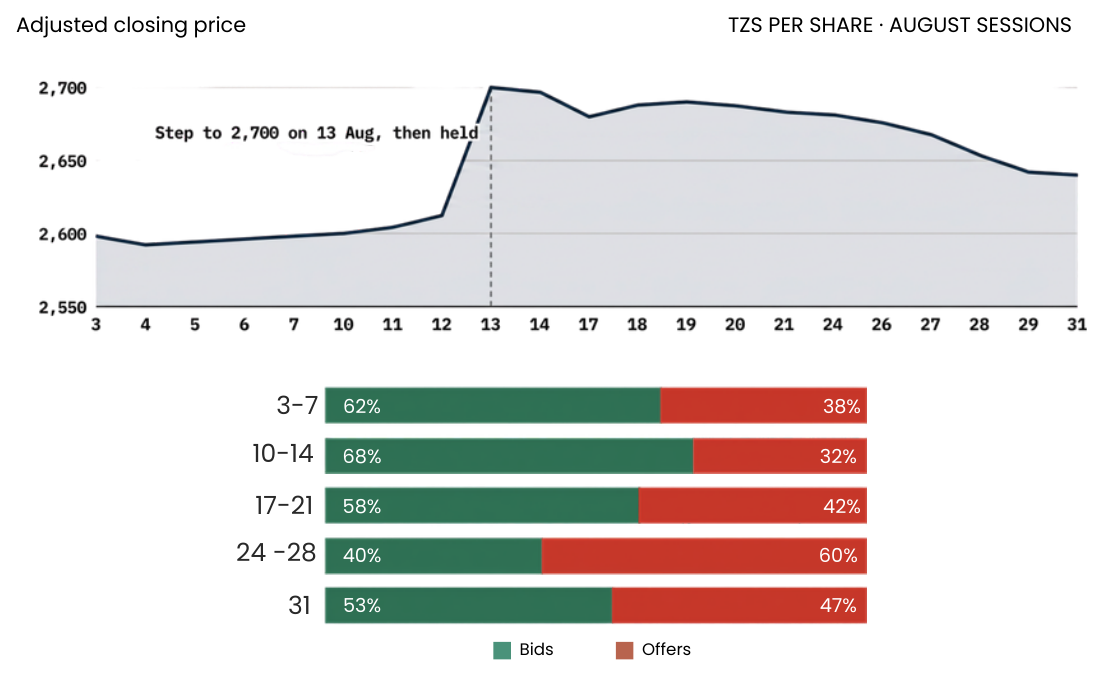
CRDB shares began August at TZS 2,600 and climbed to TZS 2,700 by 13 August before giving back most of the gain to close the month at TZS 2,640.
The counter recorded turnover of TZS 39.4 billion, or 26.9% of total August market activity, across 29,265 deals, the highest deal count of any counter reviewed.
Block trades made up 36.2% of CRDB’s turnover, including a single block of 2.28 million shares on 10 August equal to 79.5% of that day’s volume.
Kadoo believes part of CRDB’s late-month selling pressure may have reflected tactical rotation into NMB, as investors sought to participate in the post-split rally, though this interpretation rests on coincident market activity rather than confirmed investor-level flows.
High deal activity, recurring block trades and strong normal-board liquidity indicate that investors used CRDB primarily for executable exposure rather than speculative momentum.
Vodacom Tanzania Plc

Vodacom shares rose 5.0% in August on turnover of TZS 3.84 billion across 4,375 deals, with month-end bids accounting for 95.5% of the order book.
The rerating reflects an earnings inflection: Vodacom’s service revenue rose 21.7% while EBITDA expanded 37.0%, demonstrating stronger operating leverage.
Depreciation and amortisation fell 13.3%, helping net profit rise to TZS 47.3 billion from TZS 8.5 billion.
Capex nearly doubled and finance costs increased during the period, which limits how far the first-quarter profit acceleration should be extrapolated.
Vodacom’s M-Pesa mobile money platform recorded revenue growth of 26.0% as the company expanded beyond transfers into merchant payments, lending, savings and investment products.
Tanzania Cigarette Company Plc

TCC shares rose 1.6% in August, holding within a 2% monthly range on turnover of TZS 0.37 billion across just 330 deals.
Kadoo rates TCC an income buy rather than a momentum call, citing dividend support and demand for cash generation as the counter’s primary catalyst.
The key risk is excise and regulatory action: liquidity can disappear quickly when buyers step back.
TCC entered the basket because its investor motive is income, offering the highest indicative yield among the five picks while holding a narrow monthly trading range.
National Investment Company Limited

NICO shares rose 9.3% in August on turnover of TZS 3.23 billion across 1,850 deals, with month-end offers accounting for 68.2% of the order book.
The price, turnover and deal pattern are consistent with investors positioning ahead of a dividend decision, after the company last paid a dividend per share of TZS 70 for the 2024 financial year.
The research range projects an expected dividend per share of between TZS 90 and TZS 95, implying a yield of 2.3% to 2.4% at NICO’s closing price of TZS 3,940.
NICO shares also traded at a 31.7% discount to the company’s reported net asset value per share of TZS 5,770.
Kadoo rates NICO a buy, but cautions that because confirmation of the dividend is still pending and the month-end book was offer-heavy, part of the expected catalyst may already be reflected in the share price.
Corporate Event Watch: TOL Gases

TOL shares rose 38.6% in August, the largest gain of any of the six counters covered in this review, after the company’s Annual General Meeting announcement on 17 August raised expectations of a rights issue.
The stock’s rally peaked at a high of around TZS 1,990 near 27 August before easing to close the month at TZS 1,830.
Turnover reached just TZS 0.27 billion across 981 deals, and the order book shifted decisively toward offers, which accounted for 95.7% of the book by month end.
Kadoo believes investors have priced in expected balance-sheet funding and expansion optionality tied to the rights issue.
The firm keeps TOL a watch rather than one of its five picks, saying the next re-rating step needs visibility on the issue price, entitlement ratio, dilution, underwriting and use of proceeds.
Valuation Ranges Against the Month-End Close

Each pick’s 31 August closing price is compared here against an implied fair value range, to test whether the month’s price moves had already run ahead of fundamentals.
Three of the five picks, CRDB, TCC and VODA, closed within their implied value ranges, straddling the band between downside and upside scenarios.
NICO offered the widest upside, with its TZS 3,940 close implying a range of +9.9% to +46.4% against a value range of TZS 4,330 to TZS 5,770, reflecting the asset-backed gap to its reported net asset value.
NMB was the only pick trading above its implied value range, with its TZS 2,110 close sitting 3.9% above the upper band, a reading that argues for entry discipline after the split rally.
CRDB’s TZS 2,640 close implied a range of -4.9% to +21.6% against a value range of TZS 2,510 to TZS 3,210, while TCC’s TZS 12,800 close implied -6.4% to +14.4% against TZS 11,980 to TZS 14,640.
VODA’s TZS 1,050 close implied a range of -10.0% to +8.6% against a value range of TZS 945 to TZS 1,140.
Kadoo stresses that these are valuation scenarios, not price targets.
Banking Outlook and Monetary Transmission

In Kadoo’s view, rapid credit and money-supply growth should translate into stronger bank revenue momentum over the coming months.
Transferable deposits grew 43.2% year on year, while M2 money supply grew 30.1%, private sector credit grew 28.1% and M3 money supply grew 25.4%.
This is the volume effect of monetary transmission: faster private-sector credit growth expands banks’ average earning assets and supports interest income.
Growth in M3 and transferable deposits is the transaction effect, supporting payments, balances and fee-generating activity that should lift non-interest income.
Kadoo cautions that deposit pricing, net-interest margins and non-performing loan levels will determine how much of that growth ultimately reaches bank profits.

Real growth in Tanzania’s financial services sector accelerated to 20.5% year on year in the first quarter of 2026, up from 19.5% in the fourth quarter of 2025 and 14.2% in the third quarter of 2025.
The macro signal is supportive; the open question is how much of that growth converts into earnings without eroding margins or asset quality.
Download the Report
The complete Dar es Salaam Stock Exchange Market Review for August 2026 by Kadoo Securities, including the firm’s full methodology and additional data tables, is available to download here.
Disclaimer
This report was prepared by Kadoo Securities Co. Limited for general information and research purposes only, and does not constitute investment, legal, tax or accounting advice or a solicitation to buy, sell or hold any security. Kadoo Securities Research obtained the information from sources it considers reliable but does not guarantee its accuracy, and its valuation ranges should be interpreted as analytical scenarios rather than guaranteed returns or definitive price targets.
Kadoo Securities Co. Limited
Website: kadoosecurities.co.tz
General inquiries: info@kadoosecurities.co.tz
Telephone: +255 763 889 000
Research Department
Erick Sindatuma, Analyst
Email: ericksindatuma@kadoosecurities.co.tz
WhatsApp: +255 769 904 379
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free