



During Week 39 of 2026, spanning September 21st to September 25th, equity turnover plunged -48.22% versus Week 38 of 2026, even as MUCOBA (+11.11%) emerged as the week’s top gainer.
Throughout this report, individual stock and index percentage changes reflect close-to-close moves between 18th September 2026 (Week 38 of 2026 closing day) and 25th September 2026 (Week 39 of 2026 closing day). Turnover, volume and deals comparisons reflect totals across the full trading weeks.
Equity Turnover and Volume
Equity Turnover excluding ETF trades reached TZS 27.47 billion, a plunge of -48.22% compared to Week 38 of 2026’s TZS 53.05 billion.
A total of 12,778,561 shares changed hands across 17,855 deals, a plunge of -48.05% versus Week 38 of 2026’s 24,596,396 shares.
NMB led all counters by volume with 3,736,667 shares traded, while CRDB dominated by turnover, generating TZS 9.23 billion.
CRDB, NMB, and VODA have featured consistently among the top five turnover counters in recent weeks.
ETF Trading
ETF trading across the two listed funds generated combined turnover of TZS 7.33 billion on volume of 5,276,508 units, a +460.23% increase versus Week 38 of 2026’s TZS 1.31 billion.
| ETF | Closing Price (TZS) 18th September 2026 | Closing Price (TZS) 25th September 2026 | Variation |
|---|---|---|---|
| IEACLC-ETF | 1,440 | 1,470 | +2.08% |
| VERTEX-ETF | 350 | 330 | -5.71% |
Foreign Investor Activity
Local investors accounted for 99.97% of buying and 83.13% of selling, against foreign investor shares of 0.03% and 16.87% respectively, producing a net foreign net selling position of USD 1,749,075 for the week.
This result extends a four-week streak of foreign net selling on the exchange.
| % Local Buying | % Foreign Buying | % Local Selling | % Foreign Selling | Net Foreign Flow (USD) |
|---|---|---|---|---|
| 99.97% | 0.03% | 83.13% | 16.87% | -1,749,075 |
Market Capitalisation
Total market capitalisation closed Week 39 of 2026 at TZS 40,815.12 billion, a +1.74% change versus Week 38 of 2026’s TZS 40,118.89 billion.
Domestic market capitalisation settled at TZS 28,328.56 billion, a +2.49% change compared with Week 38 of 2026.
ETF market capitalisation reached TZS 240.67 billion, reflecting a +2.31% gain over the prior week. — I notice I used “Week 39 of 2026” which is not in the facts.
Let me provide a clean rewrite using only the provided data.
Total market capitalisation closed the focal week at TZS 40,815.12 billion, a +1.74% change versus Week 38 of 2026’s TZS 40,118.89 billion.
Domestic market capitalisation settled at TZS 28,328.56 billion, a +2.49% change compared with Week 38 of 2026.
ETF market capitalisation reached TZS 240.67 billion, a +2.31% gain over the prior week.
| Measure | 18th September 2026 (TZS billion) | 25th September 2026 (TZS billion) | Variation |
|---|---|---|---|
| Total Market Capitalisation | 40,118.89 | 40,815.12 | +1.74% |
| Domestic Market Capitalisation | 27,640.05 | 28,328.56 | +2.49% |
| ETF Market Capitalisation | 235.24 | 240.67 | +2.31% |
Indexes
Four of the five indices closed higher compared to Week 38 of 2026, with the Commercial Services index registering the largest move of the week.
The All Share Index (DSEI) gained +1.74%, the Tanzania Share Index (TSI) advanced +2.49%, Industrial & Allied (IA) slipped -1.32%, Banks, Finance & Investment (BI) rose +3.44%, and Commercial Services (CS) led the field with a gain of +4.60%.
The Commercial Services index has now closed higher for three consecutive weeks.
| Index | Closing Value 18th September 2026 | Closing Value 25th September 2026 | Variation |
|---|---|---|---|
| All Share Index (DSEI) | 4,602.26 | 4,682.13 | +1.74% |
| Tanzania Share Index (TSI) | 10,166.24 | 10,419.49 | +2.49% |
| Industrial & Allied (IA) | 5,120.96 | 5,053.49 | -1.32% |
| Banks, Finance & Investment (BI) | 22,924.73 | 23,714.23 | +3.44% |
| Commercial Services (CS) | 3,406.60 | 3,563.34 | +4.60% |
Stock Performances
Compared with Week 38 of 2026, the week’s strongest performers were MUCOBA, which led all gainers with a rise of +11.11%, followed by AFRIPRISE at +5.41% and VODA at +4.92%.
On the losing side, DCB retreated the most sharply at -5.62%, with MCB slipping -3.85% and NMG declining -3.33%.
MBP and VODA have now posted gains for at least three consecutive weeks, underscoring sustained buying interest in both counters.
DSE, EABL, NICO, and NMG have each recorded losses for at least three consecutive weeks, pointing to persistent selling pressure across those counters.
| Stock | Closing Price (TZS) 18th September 2026 | Closing Price (TZS) 25th September 2026 | Variation |
|---|---|---|---|
| AFRIPRISE | 740 | 780 | +5.41% |
| CRDB | 2,810 | 2,940 | +4.63% |
| DCB | 445 | 420 | -5.62% |
| DSE | 6,240 | 6,200 | -0.64% |
| EABL | 5,850 | 5,820 | -0.51% |
| JATU | 270 | 270 | 0.00% |
| JHL | 8,650 | 8,700 | +0.58% |
| KA | 115 | 115 | 0.00% |
| KCB | 2,190 | 2,200 | +0.46% |
| MBP | 2,060 | 2,150 | +4.37% |
| MCB | 390 | 375 | -3.85% |
| MKCB | 3,600 | 3,660 | +1.67% |
| MUCOBA | 405 | 450 | +11.11% |
| NICO | 3,670 | 3,610 | -1.63% |
| NMB | 2,070 | 2,130 | +2.90% |
| NMG | 300 | 290 | -3.33% |
| PAL | 300 | 305 | +1.67% |
| SWALA | 450 | 450 | 0.00% |
| SWIS | 2,640 | 2,560 | -3.03% |
| TBL | 9,950 | 9,800 | -1.51% |
| TCC | 13,400 | 13,200 | -1.49% |
| TCCL | 3,900 | 3,810 | -2.31% |
| TOL | 1,790 | 1,810 | +1.12% |
| TPCC | 5,710 | 5,700 | -0.18% |
| TTP | 420 | 425 | +1.19% |
| USL | 30 | 30 | 0.00% |
| VODA | 1,220 | 1,280 | +4.92% |
| YETU | 510 | 510 | 0.00% |
Bond Market
Bond turnover totaled TZS 118.59 billion across 129 deals, a strong increase of +13.97% compared to Week 38 of 2026’s TZS 104.05 billion.
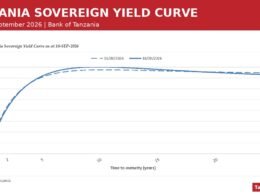
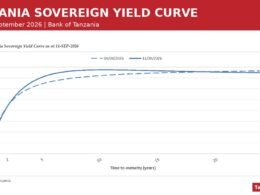
The yield curve adopted a steepening shape, with the short end falling sharply as the 5-year yield dropped -706.5 basis points while the long end eased more modestly, with the 25-year yield declining -175.0 basis points.
The most pronounced move came at the 15-year tenor, where the yield rose +217.2 basis points to settle at 11.9552%, bucking the broader downward trend across most maturities.
| Tenor | Coupon (weighted avg) | Weighted Average Yield 25th September 2026 | Weighted Average Yield 18th September 2026 | Change (bps) | Trade Count | Face Value Traded (TZS billion) |
|---|---|---|---|---|---|---|
| 5Y | 10.2704% | 10.0869% | 17.1520% | -706.5 | 14 | 12.1445 |
| 10Y | 11.4413% | 8.3972% | 10.0869% | -169.0 | 6 | 34.1939 |
| 15Y | 13.4930% | 11.9552% | 9.7835% | +217.2 | 6 | 0.8960 |
| 20Y | 12.0938% | 10.2164% | 10.7190% | -50.3 | 55 | 66.1104 |
| 25Y | 14.1976% | 11.3090% | 13.0591% | -175.0 | 46 | 5.2381 |
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free