



During Week 40 of 2026, spanning September 28th to October 2nd, equity turnover held roughly steady at TZS 27.87 billion, up +1.47% from Week 39 of 2026, with NMG (+8.62%) emerging as the top gainer of the week.
Throughout this report, individual stock and index percentage changes reflect close-to-close moves between 25th September 2026 (Week 39 of 2026 closing day) and 2nd October 2026 (Week 40 of 2026 closing day). Turnover, volume and deals comparisons reflect totals across the full trading weeks.
Equity Turnover and Volume
Equity Turnover excluding ETF trades reached TZS 27.87 billion, a near-flat reading of +1.47% compared to Week 39 of 2026’s TZS 27.47 billion.
A total of 11,669,579 shares changed hands across 18,546 deals, a decline of -8.68% versus Week 39 of 2026’s 12,778,561 shares.
CRDB led all counters by volume with 5,918,767 shares traded, while CRDB dominated by turnover, generating TZS 15.80 billion.
NMB, CRDB, and VODA retained their positions among the top five counters by turnover across recent weeks.
ETF Trading
ETF trading across the two listed funds generated combined turnover of TZS 799.10 million on volume of 798,056 units, a -89.09% decline versus Week 39 of 2026’s TZS 7.33 billion.
| ETF | Closing Price (TZS) 25th September 2026 | Closing Price (TZS) 2nd October 2026 | Variation |
|---|---|---|---|
| IEACLC-ETF | 1,470 | 1,460 | -0.68% |
| VERTEX-ETF | 330 | 325 | -1.52% |
Foreign Investor Activity
Local investors accounted for 83.02% of buying and 78.15% of selling, against foreign investor shares of 16.98% and 21.85% respectively, producing a net foreign net selling position of USD 514,148 for the week.
This result extends a four-week streak of foreign net selling on the exchange.
| % Local Buying | % Foreign Buying | % Local Selling | % Foreign Selling | Net Foreign Flow (USD) |
|---|---|---|---|---|
| 83.02% | 16.98% | 78.15% | 21.85% | -514,148 |
Market Capitalisation
Total market capitalisation closed Week 40 of 2026 at TZS 40,376.17 billion, a -1.08% change versus Week 39 of 2026’s TZS 40,815.12 billion.
Domestic market capitalisation settled at TZS 27,882.97 billion, reflecting a -1.57% decline from Week 39 of 2026.
| Measure | 25th September 2026 (TZS billion) | 2nd October 2026 (TZS billion) | Variation |
|---|---|---|---|
| Total Market Capitalisation | 40,815.12 | 40,376.17 | -1.08% |
| Domestic Market Capitalisation | 28,328.56 | 27,882.97 | -1.57% |
| ETF Market Capitalisation | 240.67 | 238.89 | -0.74% |
Indexes
Four of the five DSE indices retreated from Week 39 of 2026 levels, with Banks, Finance & Investment posting the steepest decline as the biggest mover.
The All Share Index (DSEI) slipped -1.08%, the Tanzania Share Index (TSI) fell -1.57%, Industrial & Allied (IA) edged up +0.43%, Banks, Finance & Investment (BI) dropped -2.22%, and Commercial Services (CS) declined -1.56%.
| Index | Closing Value 25th September 2026 | Closing Value 2nd October 2026 | Variation |
|---|---|---|---|
| All Share Index (DSEI) | 4,682.13 | 4,631.77 | -1.08% |
| Tanzania Share Index (TSI) | 10,419.49 | 10,255.60 | -1.57% |
| Industrial & Allied (IA) | 5,053.49 | 5,075.25 | +0.43% |
| Banks, Finance & Investment (BI) | 23,714.23 | 23,188.19 | -2.22% |
| Commercial Services (CS) | 3,563.34 | 3,507.72 | -1.56% |
Stock Performances
NMG led the weekly gainers with a rise of +8.62%, followed by NICO at +4.43% and TCCL at +3.67%, each compared with Week 39 of 2026.
On the losing side, MBP shed -7.44%, DCB fell -4.76%, and AFRIPRISE declined -4.49% over the same period.
SWIS, TBL, and TPCC have each recorded losses for at least three consecutive weeks, pointing to sustained selling pressure across those counters.
| Stock | Closing Price (TZS) 25th September 2026 | Closing Price (TZS) 2nd October 2026 | Variation |
|---|---|---|---|
| AFRIPRISE | 780 | 745 | -4.49% |
| CRDB | 2,940 | 2,950 | +0.34% |
| DCB | 420 | 400 | -4.76% |
| DSE | 6,200 | 6,350 | +2.42% |
| EABL | 5,820 | 5,860 | +0.69% |
| JATU | 270 | 270 | 0.00% |
| JHL | 8,700 | 8,700 | 0.00% |
| KA | 115 | 115 | 0.00% |
| KCB | 2,200 | 2,190 | -0.45% |
| MBP | 2,150 | 1,990 | -7.44% |
| MCB | 375 | 370 | -1.33% |
| MKCB | 3,660 | 3,680 | +0.55% |
| MUCOBA | 450 | 450 | 0.00% |
| NICO | 3,610 | 3,770 | +4.43% |
| NMB | 2,130 | 2,040 | -4.23% |
| NMG | 290 | 315 | +8.62% |
| PAL | 305 | 305 | 0.00% |
| SWALA | 450 | 450 | 0.00% |
| SWIS | 2,560 | 2,500 | -2.34% |
| TBL | 9,800 | 9,780 | -0.20% |
| TCC | 13,200 | 13,350 | +1.14% |
| TCCL | 3,810 | 3,950 | +3.67% |
| TOL | 1,810 | 1,730 | -4.42% |
| TPCC | 5,700 | 5,670 | -0.53% |
| TTP | 425 | 430 | +1.18% |
| USL | 30 | 30 | 0.00% |
| VODA | 1,280 | 1,260 | -1.56% |
| YETU | 510 | 510 | 0.00% |
Bond Market
Bond turnover totaled TZS 82.69 billion across 78 deals, a plunge of -30.27% compared to Week 39 of 2026’s TZS 118.59 billion.
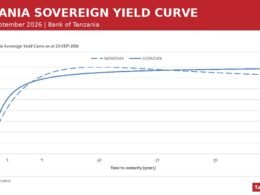
The yield curve exhibited a flattening bias, with the 5-year yield rising sharply by 268.7 basis points while the 25-year yield edged up a modest 9.7 basis points.
The most pronounced move came at the short end, where the 5-year tenor surged to a yield of 12.7737%, reflecting the steepest week-on-week shift across the curve.
| Tenor | Coupon (weighted avg) | Weighted Average Yield 2nd October 2026 | Weighted Average Yield 25th September 2026 | Change (bps) | Trade Count | Face Value Traded (TZS billion) |
|---|---|---|---|---|---|---|
| 5Y | 12.0000% | 12.7737% | 10.0869% | +268.7 | 4 | 0.0520 |
| 10Y | 11.4370% | 8.0845% | 8.3972% | -31.3 | 4 | 20.0760 |
| 15Y | 12.2838% | 10.4882% | 11.9552% | -146.7 | 16 | 25.9185 |
| 20Y | 15.2783% | 10.7209% | 10.2164% | +50.5 | 28 | 33.4126 |
| 25Y | 14.7728% | 11.4055% | 11.3090% | +9.7 | 25 | 3.2213 |
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free