


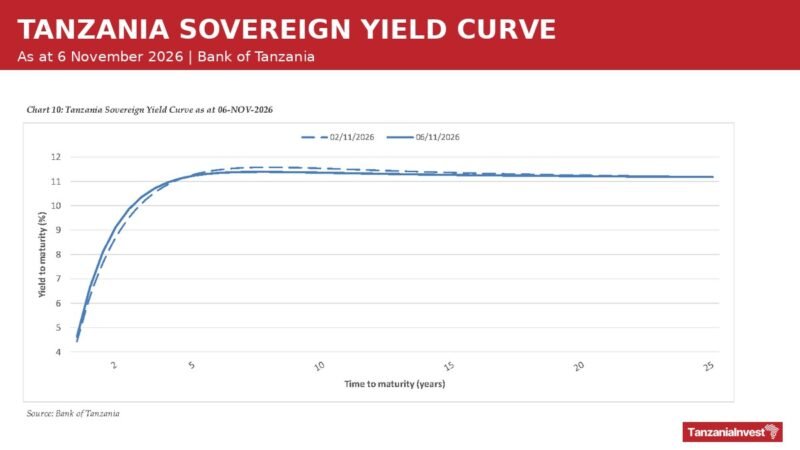
Tanzania’s financial markets closed the week to 6 November 2026 with the 2-year Treasury bond yield falling to 8.0919%, down from 8.4033% at the previous auction of the same tenor.
The Bank of Tanzania (BOT) released the figures on 9 November 2026 in the eleventh issue of its Domestic Financial Markets Weekly Report, a publication it launched on 2 September 2026 and now issues weekly.
The report brings together foreign exchange market, money market and government securities data for the week in a single release, alongside charts of monthly and fiscal-year trends.
Government Securities
The 9.5% 2-year Treasury bond No. 712, maturing on 30 July 2028, attracted 75 bids at the auction held on 4 November 2026, of which 44 were successful.
Investors tendered TZS 394.94 billion against an offered amount of TZS 138.95 billion, an oversubscription of TZS 255.99 billion that produced a bid-to-cover ratio of 2.84x, with total allotment reaching TZS 136.94 billion.
The minimum successful price was 101.3949 and the weighted average price 102.2098, leaving the weighted average yield to maturity 31.14 basis points below the level recorded at the preceding auction of the same tenor.
Banks submitted 52.92% of subscriptions and took almost the entire allotment at TZS 135.44 billion, equivalent to 98.90% of the total awarded at the auction.
Collective Investment Schemes accounted for 44.34% of subscriptions but received no allotment, while Insurance Companies submitted 2.74% of subscriptions and were allotted TZS 1.50 billion, or 1.10% of the total.
Outstanding Government Securities stood at TZS 34,377.78 billion, comprising Treasury bonds worth TZS 30,966.42 billion, or 90.08% of the total, and Treasury bills worth TZS 3,411.36 billion, or 9.92%.
Banks held the largest share of that stock at 33.97%, worth TZS 11,678.76 billion, followed by Pension Funds at 29.90%, worth TZS 10,278.63 billion.
Retail Investors held 17.89% worth TZS 6,151.39 billion, Collective Investment Schemes and other official entities 8.08% worth TZS 2,777.70 billion, and Insurance Companies 7.34% worth TZS 2,522.51 billion.
The Bank onboarded 4,549 new clients in the current fiscal year, lifting the total number of registered investors in government securities to 36,051.
The next government securities auction is scheduled for Wednesday 11 November 2026, when a 10-Year Treasury bond will be offered in line with the issuance calendar.
Foreign Exchange Market
The shilling held steady over the week, appreciating 0.01% to close at TZS 2,640.44 against the US dollar, from TZS 2,640.73 at the end of the previous week.
Turnover on the Interbank Foreign Exchange Market (IFEM) fell sharply to USD 19.10 million from USD 58.50 million a week earlier, a decline of more than two thirds.
Retail foreign exchange transactions decreased to USD 604.10 million from USD 713.39 million recorded across the commercial banks in the previous week.
Trade accounted for the largest share of retail turnover at USD 164.80 million, followed by Mining at USD 77.23 million and Agriculture at USD 75.06 million, together representing USD 317.09 million.
The mining sector’s retail turnover nearly halved to USD 77.23 million from USD 150.96 million a week earlier, driven by a drop in its foreign currency purchases to USD 58.54 million.
Daily retail foreign exchange transactions averaged USD 132.91 million over the past month, with sales averaging USD 63.68 million and purchases averaging USD 69.23 million.
Against other currencies the shilling closed at TZS 3,553.77 to the British Pound Sterling, TZS 2,963.63 to the Euro, TZS 395.94 to the Chinese Yuan and TZS 20.3111 to the Kenyan Shilling.
Money Market
The Interbank Cash Market (IBCM) 7-day Weighted Average Rate (WAR) closed the week at 6.38%, down from 6.55% recorded at the close of the previous week.
Total 7-day trading volume increased to TZS 758.65 billion from TZS 670.05 billion recorded in the preceding week, according to the report.
The 7-day weekly WAR averaged 6.33%, sitting 8 basis points above the Central Bank Rate (CBR) of 6.25% and inside the corridor of 4.75% to 7.75%.
The Bank injected TZS 774.96 billion through 7-day reverse repurchase agreements at the CBR of 6.25%, up from TZS 768.20 billion injected in the preceding week.
Bank of Tanzania Monetary Policy Framework
BOT adopted an interest rate based monetary policy framework in January 2024, replacing the monetary targeting regime under which it had previously steered reserve money.
Under that framework the Central Bank Rate is the policy rate, while the 7-day interbank cash market rate serves as the operating target the Bank steers towards it.
The main instruments are repurchase agreements, 35-day and 91-day Treasury bills, the statutory minimum reserve requirement, and purchases or sales of foreign currency in the interbank market.
The Monetary Policy Committee maintained the Central Bank Rate at 6.25% for the fourth quarter of 2026, with GDP growth projected at 7.2% for the quarter, driven by agriculture, construction, mining and tourism.
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free