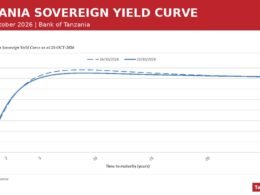



Tanzania’s financial markets closed the week to 30 October 2026 with the 20-year Treasury bond yield falling to 10.5214%, down from 11.3306% at the previous auction of the same tenor.
The Bank of Tanzania (BOT) released the figures on 2 November 2026 in its tenth Domestic Financial Markets Weekly Report, a publication it launched on 2 September 2026 and now issues weekly.
The report brings together foreign exchange market, money market and government securities data for the trading week that began on 26 October 2026 in a single release, alongside charts of monthly and fiscal-year trends.
Government Securities
The 12.25% 20-year Treasury bond No. 710, maturing on 9 July 2046, attracted 1,356 bids at the auction held on 28 October 2026, of which 861 were successful.
Investors tendered TZS 1,033.09 billion against an offered amount of TZS 363.01 billion, an oversubscription of TZS 670.08 billion that produced a bid-to-cover ratio of 2.85x, with total allotment reaching TZS 336.62 billion.
The minimum successful price was 111.8071 and the weighted average price 114.2114, leaving the weighted average yield to maturity 80.92 basis points below the level recorded at the preceding auction of the same tenor.
Individuals and Companies took the largest share of the allotment at TZS 156.09 billion, equivalent to 46.37% of the total, from 36.88% of subscriptions submitted during the sale.
Banks submitted 22.48% of subscriptions and were allotted TZS 92.60 billion, or 27.51% of the total, while Pension Funds received 22.18% of the allotment from 14.09% of subscriptions.
Collective Investment Schemes accounted for 25.46% of subscriptions but were allotted only TZS 1.99 billion, representing 0.59% of the total, while Insurance Companies received 3.35% from 1.09% of subscriptions.
Outstanding Government Securities stood at TZS 34,474.24 billion, comprising Treasury bonds worth TZS 30,829.48 billion, or 89.43% of the total, and Treasury bills worth TZS 3,644.76 billion, or 10.57%.
Banks held the largest share of that stock at 34.28%, worth TZS 11,816.77 billion, followed by Pension Funds at 29.70%, worth TZS 10,238.61 billion at face value.
Retail Investors held 17.86% worth TZS 6,158.58 billion, Collective Investment Schemes and other official entities 8.04% worth TZS 2,770.65 billion, and Insurance Companies 7.31% worth TZS 2,519.31 billion.
The Bank onboarded 4,290 new clients in the current fiscal year, lifting the total number of registered investors in government securities to 35,792 across the market.
The next government securities auction is scheduled for Wednesday 4 November 2026, when a 2-year Treasury bond will be offered in line with the issuance calendar.
Foreign Exchange Market
The shilling depreciated 0.15% over the week to close at TZS 2,640.73 against the US dollar, from TZS 2,636.74 at the end of the previous week.
Turnover on the Interbank Foreign Exchange Market (IFEM) declined to USD 58.50 million from USD 60.80 million a week earlier, while retail foreign exchange transactions rose to USD 713.39 million from USD 575.68 million.
Trade accounted for the largest share of retail turnover at USD 201.33 million, followed by Mining at USD 150.96 million and Oil & Energy at USD 69.10 million, together representing USD 421.38 million.
The mining sector’s foreign currency purchases surged more than fivefold to USD 136.98 million from USD 26.08 million a week earlier, the sharpest sectoral movement recorded in the period.
Daily retail foreign exchange transactions averaged USD 130.67 million over the past month, with sales averaging USD 63.10 million and purchases averaging USD 67.57 million across the market.
Against other currencies the shilling closed at TZS 3,516.66 to the British Pound Sterling, TZS 2,937.55 to the Euro, TZS 396.39 to the Chinese Yuan and TZS 20.2977 to the Kenyan Shilling.
Money Market
The Interbank Cash Market (IBCM) 7-day Weighted Average Rate (WAR) closed the week at 6.55%, down from 6.59% recorded at the close of the previous week.
Total 7-day trading volume increased to TZS 670.05 billion from TZS 587.45 billion recorded in the preceding week, according to the report.
The 7-day weekly WAR averaged 6.38%, sitting 13 basis points above the Central Bank Rate (CBR) of 6.25% and inside the corridor of 4.75% to 7.75%.
The Bank injected TZS 768.20 billion through 7-day reverse repurchase agreements at the CBR of 6.25%, down from TZS 774.96 billion injected in the preceding week.
Bank of Tanzania Monetary Policy Framework
BOT adopted an interest rate based monetary policy framework in January 2024, replacing the monetary targeting regime under which it had previously steered reserve money as its anchor.
Under that framework the Central Bank Rate serves as the policy rate, while the 7-day interbank cash market rate is the operating target the Bank steers towards it.
The main instruments comprise repurchase agreements, 35-day and 91-day Treasury bills, the statutory minimum reserve requirement, and purchases or sales of foreign currency in the interbank market.
The Monetary Policy Committee maintained the CBR at 6.25% for the fourth quarter of 2026, with GDP growth projected at 7.2% and driven by agriculture, construction, mining and tourism.
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free