


During Week 44 of 2026, spanning October 26th to October 30th, equity turnover surged +147.30% compared with Week 43 of 2026, with NMG (+30.23%) emerging as the week’s top gainer.
Throughout this report, individual stock and index percentage changes reflect close-to-close moves between 23rd October 2026 (Week 43 of 2026 closing day) and 30th October 2026 (Week 44 of 2026 closing day). Turnover, volume and deals comparisons reflect totals across the full trading weeks.
Equity Turnover and Volume
Equity Turnover excluding ETF trades reached TZS 41.66 billion, a surge of +147.30% compared to Week 43 of 2026’s TZS 16.85 billion.
A total of 18,522,653 shares changed hands across 18,746 deals, a surge of +100.01% versus Week 43 of 2026’s 9,260,962 shares.
NMB led all counters by volume with 11,705,243 shares traded, while NMB dominated by turnover, generating TZS 21.30 billion.
CRDB, NMB, NICO, and VODA have been persistent fixtures in the top five turnover counters across recent weeks.
ETF Trading
ETF trading across the three listed funds generated combined turnover of TZS 2.28 billion on volume of 9,745,765 units, a +339.28% increase versus Week 43 of 2026’s TZS 519.30 million.
| ETF | Closing Price (TZS) 23rd October 2026 | Closing Price (TZS) 30th October 2026 | Variation |
|---|---|---|---|
| IEACLC-ETF | 1,430 | 1,390 | -2.80% |
| VERTEX-ETF | 310 | 315 | +1.61% |
| ZAN TIMIZA ETF | 105 | 120 | +14.29% |
Foreign Investor Activity
Local investors accounted for 93.04% of buying and 31.44% of selling, against foreign investor shares of 6.96% and 68.56% respectively, producing a net foreign net selling position of USD 9,718,805 for the week.
This result extends a four-week streak of foreign net selling on the exchange.
| % Local Buying | % Foreign Buying | % Local Selling | % Foreign Selling | Net Foreign Flow (USD) |
|---|---|---|---|---|
| 93.04% | 6.96% | 31.44% | 68.56% | -9,718,805 |
Market Capitalisation
Total market capitalisation closed at TZS 38,567.91 billion, a -2.53% change versus Week 43 of 2026’s TZS 39,569.88 billion.
Domestic market capitalisation settled at TZS 26,742.63 billion, reflecting a -2.75% change from Week 43 of 2026.
| Measure | 23rd October 2026 (TZS billion) | 30th October 2026 (TZS billion) | Variation |
|---|---|---|---|
| Total Market Capitalisation | 39,569.88 | 38,567.91 | -2.53% |
| Domestic Market Capitalisation | 27,499.03 | 26,742.63 | -2.75% |
| ETF Market Capitalisation | 243.47 | 239.12 | -1.79% |
Indexes
Three of the five tracked indices closed lower compared to Week 43 of 2026, with Banks, Finance & Investment registering the sharpest move at -4.49%.
The All Share Index (DSEI) fell -2.53%, the Tanzania Share Index (TSI) declined -2.75%, Banks, Finance & Investment (BI) dropped -4.49%, while Industrial & Allied (IA) edged up +0.81% and Commercial Services (CS) gained +0.19%.
The DSEI and BI have now each fallen for four consecutive weeks, while IA has posted gains for three straight weeks.
| Index | Closing Value 23rd October 2026 | Closing Value 30th October 2026 | Variation |
|---|---|---|---|
| All Share Index (DSEI) | 4,539.27 | 4,424.33 | -2.53% |
| Tanzania Share Index (TSI) | 10,114.38 | 9,836.17 | -2.75% |
| Industrial & Allied (IA) | 5,286.69 | 5,329.55 | +0.81% |
| Banks, Finance & Investment (BI) | 22,436.18 | 21,428.71 | -4.49% |
| Commercial Services (CS) | 3,469.51 | 3,476.20 | +0.19% |
Stock Performances
NMG led all advancers with a gain of +30.23%, followed by PAL at +5.45% and TTP at +4.00%, all measured against Week 43 of 2026.
On the losing side, USL retreated -16.67%, MBP fell -8.96%, and NMB declined -6.67% over the same period.
TCC and TCCL have each recorded gains for at least three consecutive weeks.
EABL, KCB, MCB, NICO, NMB, and TOL have each posted losses for at least three consecutive weeks.
| Stock | Closing Price (TZS) 23rd October 2026 | Closing Price (TZS) 30th October 2026 | Variation |
|---|---|---|---|
| AFRIPRISE | 750 | 750 | 0.00% |
| CRDB | 2,900 | 2,840 | -2.07% |
| DCB | 390 | 400 | +2.56% |
| DSE | 6,100 | 6,140 | +0.66% |
| EABL | 5,500 | 5,400 | -1.82% |
| JATU | 200 | 200 | 0.00% |
| JHL | 8,700 | 8,700 | 0.00% |
| KA | 115 | 110 | -4.35% |
| KCB | 2,150 | 2,100 | -2.33% |
| MBP | 2,120 | 1,930 | -8.96% |
| MCB | 370 | 365 | -1.35% |
| MKCB | 3,660 | 3,580 | -2.19% |
| MUCOBA | 400 | 400 | 0.00% |
| NICO | 3,420 | 3,400 | -0.58% |
| NMB | 1,950 | 1,820 | -6.67% |
| NMG | 215 | 280 | +30.23% |
| PAL | 275 | 290 | +5.45% |
| SWALA | 450 | 450 | 0.00% |
| SWIS | 2,360 | 2,450 | +3.81% |
| TBL | 10,300 | 10,260 | -0.39% |
| TCC | 14,000 | 14,250 | +1.79% |
| TCCL | 4,200 | 4,350 | +3.57% |
| TOL | 1,540 | 1,470 | -4.55% |
| TPCC | 5,710 | 5,780 | +1.23% |
| TTP | 375 | 390 | +4.00% |
| USL | 30 | 25 | -16.67% |
| VODA | 1,250 | 1,250 | 0.00% |
| YETU | 510 | 510 | 0.00% |
Bond Market
Bond turnover totaled TZS 118.29 billion across 178 deals, a sharp decline of -23.74% compared to Week 43 of 2026’s TZS 155.12 billion.
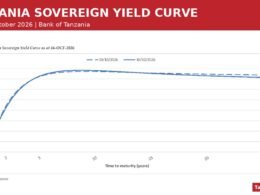
The yield curve flattened as the 5-year tenor rose +52.2 basis points while the 25-year tenor eased -4.8 basis points, compressing the spread between short and long maturities.
The most pronounced move came at the 15-year tenor, where yields surged +218.2 basis points to reach 12.3158%, the steepest single-tenor shift across the curve.
| Tenor | Coupon (weighted avg) | Weighted Average Yield 30th October 2026 | Weighted Average Yield 23rd October 2026 | Change (bps) | Trade Count | Face Value Traded (TZS billion) |
|---|---|---|---|---|---|---|
| 5Y | 12.9973% | 10.7748% | 10.2524% | +52.2 | 9 | 20.0595 |
| 10Y | 10.5086% | 10.6542% | 10.8213% | -16.7 | 4 | 3.0323 |
| 15Y | 12.2997% | 12.3158% | 10.1336% | +218.2 | 8 | 0.4313 |
| 20Y | 14.0715% | 10.9380% | 11.2239% | -28.6 | 48 | 36.2251 |
| 25Y | 13.5293% | 10.7451% | 10.7932% | -4.8 | 101 | 27.4041 |
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free