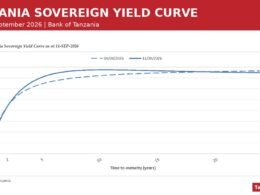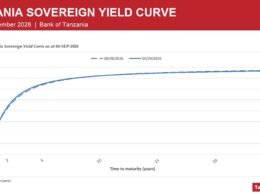


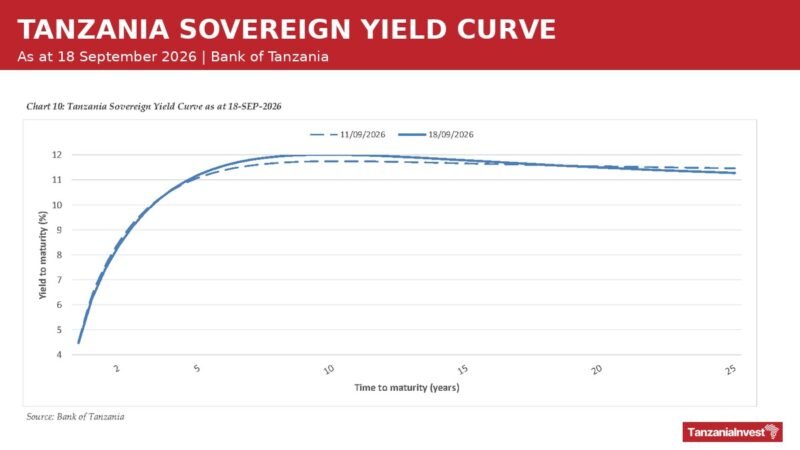
Tanzania’s financial markets closed the week to 18 September 2026 with the 5-year Treasury bond yield falling sharply to 9.5275%, down from 10.3861% recorded at the previous auction of the same tenor.
The Bank of Tanzania (BOT) released the figures on 21 September 2026 in its fourth Domestic Financial Markets Weekly Report, a publication it launched on 2 September 2026 and now issues weekly.
The report consolidates foreign exchange market, money market and government securities data for the trading week of 14 to 18 September 2026, alongside charts of monthly and fiscal-year trends.
Government Securities
The 10.25% 5-year Treasury bond No. 700, maturing on 30 April 2031, attracted 100 bids at the auction held on 16 September 2026, of which 75 were successful.
Investors tendered TZS 398.06 billion against an offered amount of TZS 145.63 billion, an oversubscription of TZS 252.43 billion that produced a bid-to-cover ratio of 2.73x, with total allotment reaching TZS 143.57 billion.
The minimum successful price was 100.1576 and the weighted average price 102.6275, leaving the weighted average yield to maturity 85.86 basis points below the level recorded at the preceding auction of the same tenor.
Banks dominated the auction with 44.59% of subscriptions and took TZS 138.65 billion of the allotment, equivalent to 96.57% of the total awarded during the sale.
Collective Investment Schemes submitted 25.88% of subscriptions but received no allotment, while Pension Funds accounted for 17.77% of subscriptions and were awarded TZS 0.70 billion, or 0.48% of the total.
Individuals and Companies accounted for 10.80% of subscriptions and 0.64% of the allotment, while Insurance Companies submitted 0.96% of subscriptions and received 2.31% of the total awarded.
Outstanding Government Securities stood at TZS 33,036.90 billion, comprising Treasury bonds worth TZS 29,805.15 billion, or 90.22% of the total, and Treasury bills worth TZS 3,231.75 billion, or 9.78%.
Banks held the largest share of that stock at 33.25%, worth TZS 10,985.28 billion, followed by Pension Funds at 30.48%, worth TZS 10,068.80 billion.
Retail Investors held 17.72% worth TZS 5,853.79 billion, Collective Investment Schemes and other official entities 8.20% worth TZS 2,709.14 billion, and Insurance Companies 7.42% worth TZS 2,449.94 billion.
The Bank onboarded 2,300 new clients in the current fiscal year, lifting the total number of registered investors in government securities to 33,802.
The next government securities auction is scheduled for Wednesday 23 September 2026, when Treasury bills will be offered in line with the issuance calendar.
Foreign Exchange Market
The shilling weakened 0.13% over the week to close at TZS 2,641.34 against the US dollar, from TZS 2,637.97 at the end of the previous week.
Turnover on the Interbank Foreign Exchange Market (IFEM) rose to USD 35.50 million from USD 27.30 million a week earlier, while retail foreign exchange transactions edged up to USD 536.53 million from USD 535.00 million.
Trade accounted for the largest share of retail turnover at USD 160.26 million, followed by Oil & Energy at USD 68.71 million and Individual Retail Customers at USD 65.34 million, together representing USD 294.30 million.
The mining sector’s foreign currency purchases rose to USD 56.56 million from USD 36.33 million a week earlier, lifting its total retail turnover to USD 59.49 million from USD 44.35 million.
Daily retail foreign exchange transactions averaged USD 130.32 million over the past month, with sales averaging USD 65.14 million and purchases averaging USD 65.18 million.
Against other currencies the shilling closed at TZS 3,533.06 to the British Pound Sterling, TZS 3,034.90 to the Euro, TZS 393.78 to the Chinese Yuan and TZS 20.37 to the Kenyan Shilling.
Money Market
The Interbank Cash Market (IBCM) 7-day Weighted Average Rate (WAR) closed the week at 6.72%, down from 6.75% recorded at the close of the previous week.
Total 7-day trading volume increased to TZS 712.35 billion from TZS 652.35 billion recorded in the preceding week, according to the report.
The 7-day weekly WAR averaged 6.57%, sitting 32 basis points above the Central Bank Rate (CBR) of 6.25% and inside the corridor of 4.75% to 7.75%.
The Bank injected TZS 852.00 billion through 7-day reverse repurchase agreements at the CBR of 6.25%, up from TZS 654.50 billion injected in the preceding week.
Bank of Tanzania Monetary Policy Framework
BOT adopted an interest rate based monetary policy framework in January 2024, moving away from the monetary targeting regime under which it had previously controlled the supply of reserve money.
Within that framework the Central Bank Rate serves as the policy rate, while the 7-day interbank cash market rate is the operating target that the Bank guides towards it.
Its principal instruments include repurchase and reverse repurchase agreements, 35-day and 91-day Treasury bills, the statutory minimum reserve requirement, and interventions in the interbank foreign exchange market.
The Monetary Policy Committee set the Central Bank Rate at 6.25% for the third quarter of 2026, defining the interbank rate corridor of 4.75% to 7.75% within which the week’s weighted average rate settled.
Want to know more about Capital Markets in Tanzania? Our upcoming Capital Markets Guide covers the Dar es Salaam Stock Exchange (DSE), listed companies, bonds, and private equity, plus the regulatory framework for investing in Tanzania’s capital markets.
Learn MoreWant to know more about the Capital Markets in Tanzania? Our free overview of the Tanzania Business and Investment Guide 2026 covers the Capital Markets, plus key sectors and investment opportunities. The complete 141-page edition includes policies, taxation, key regulations, full macroeconomic data, and sources, and is also available at no cost upon completion of a short form.
Download Free OverviewGet the Full Edition for Free